Mortgage Payment Calculator
The monthly payment on a listing: principal and interest, property tax, insurance, dues and mortgage insurance.
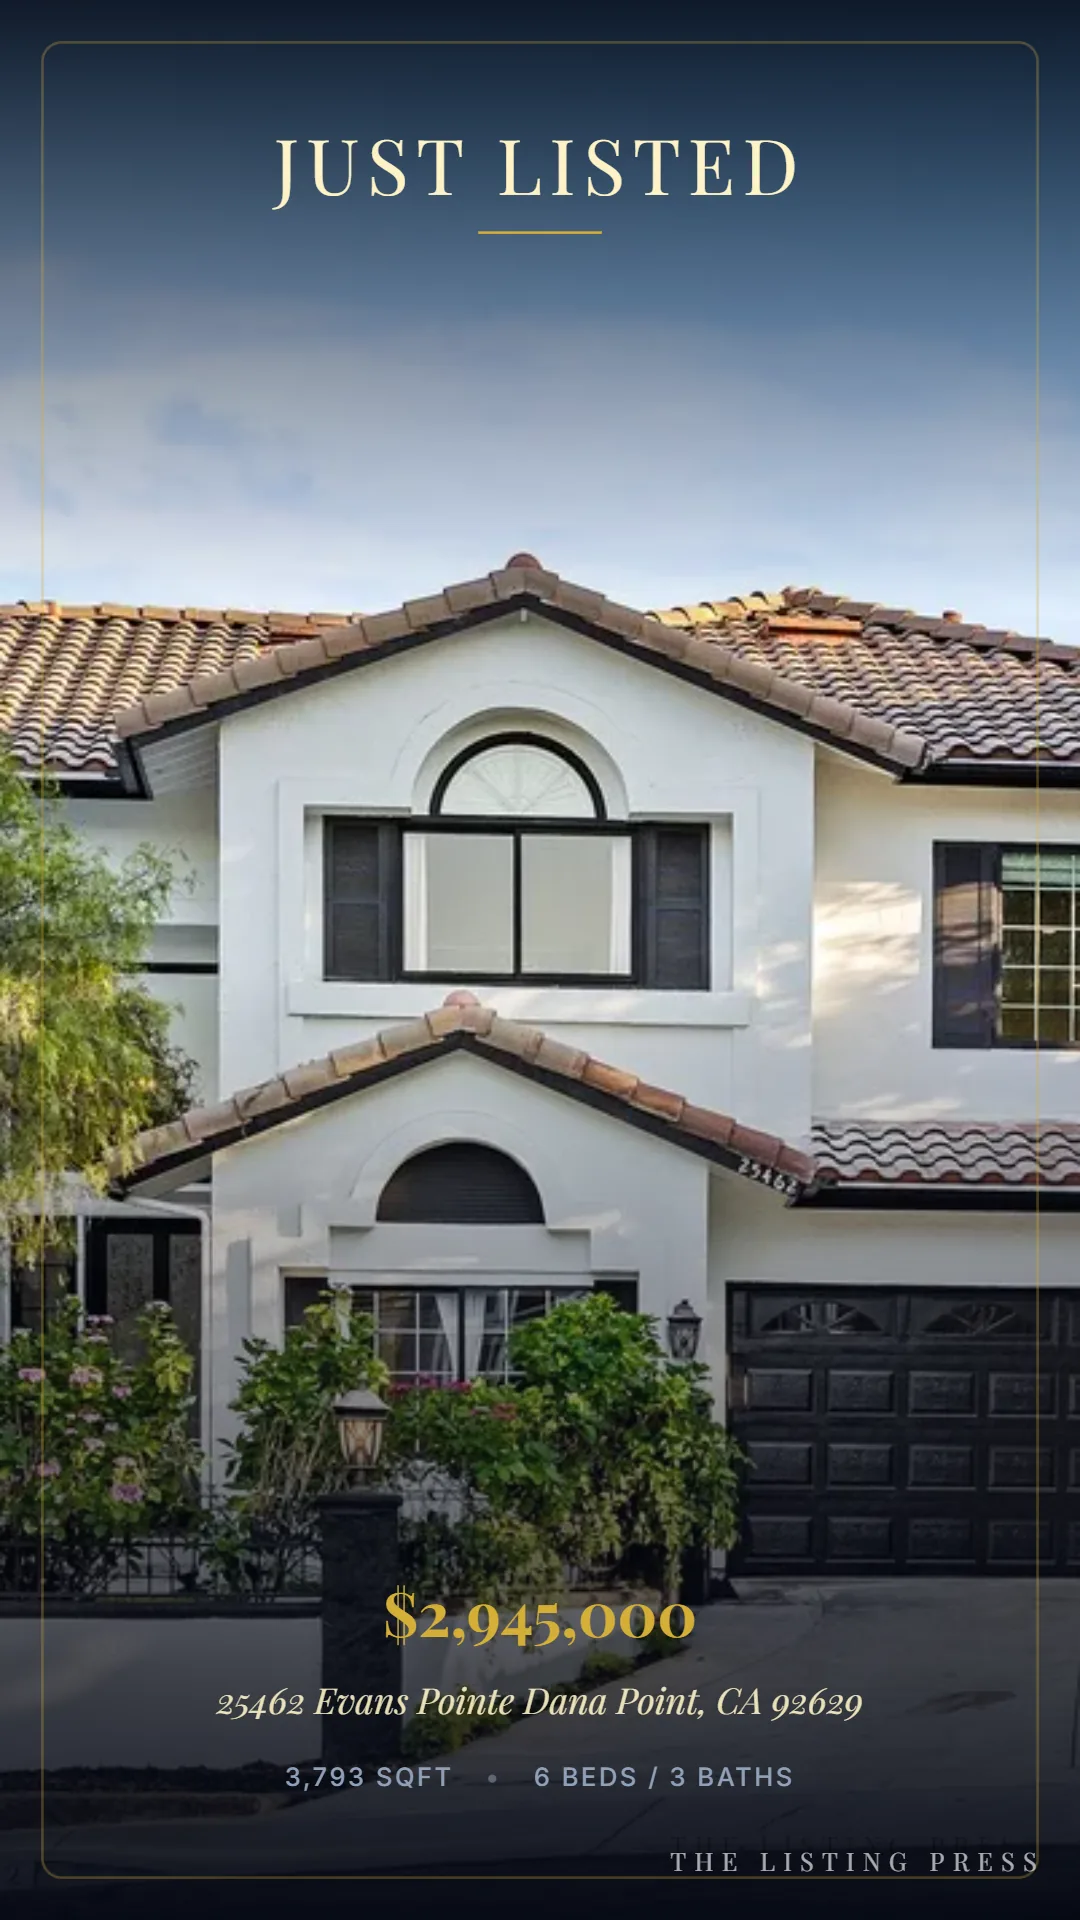
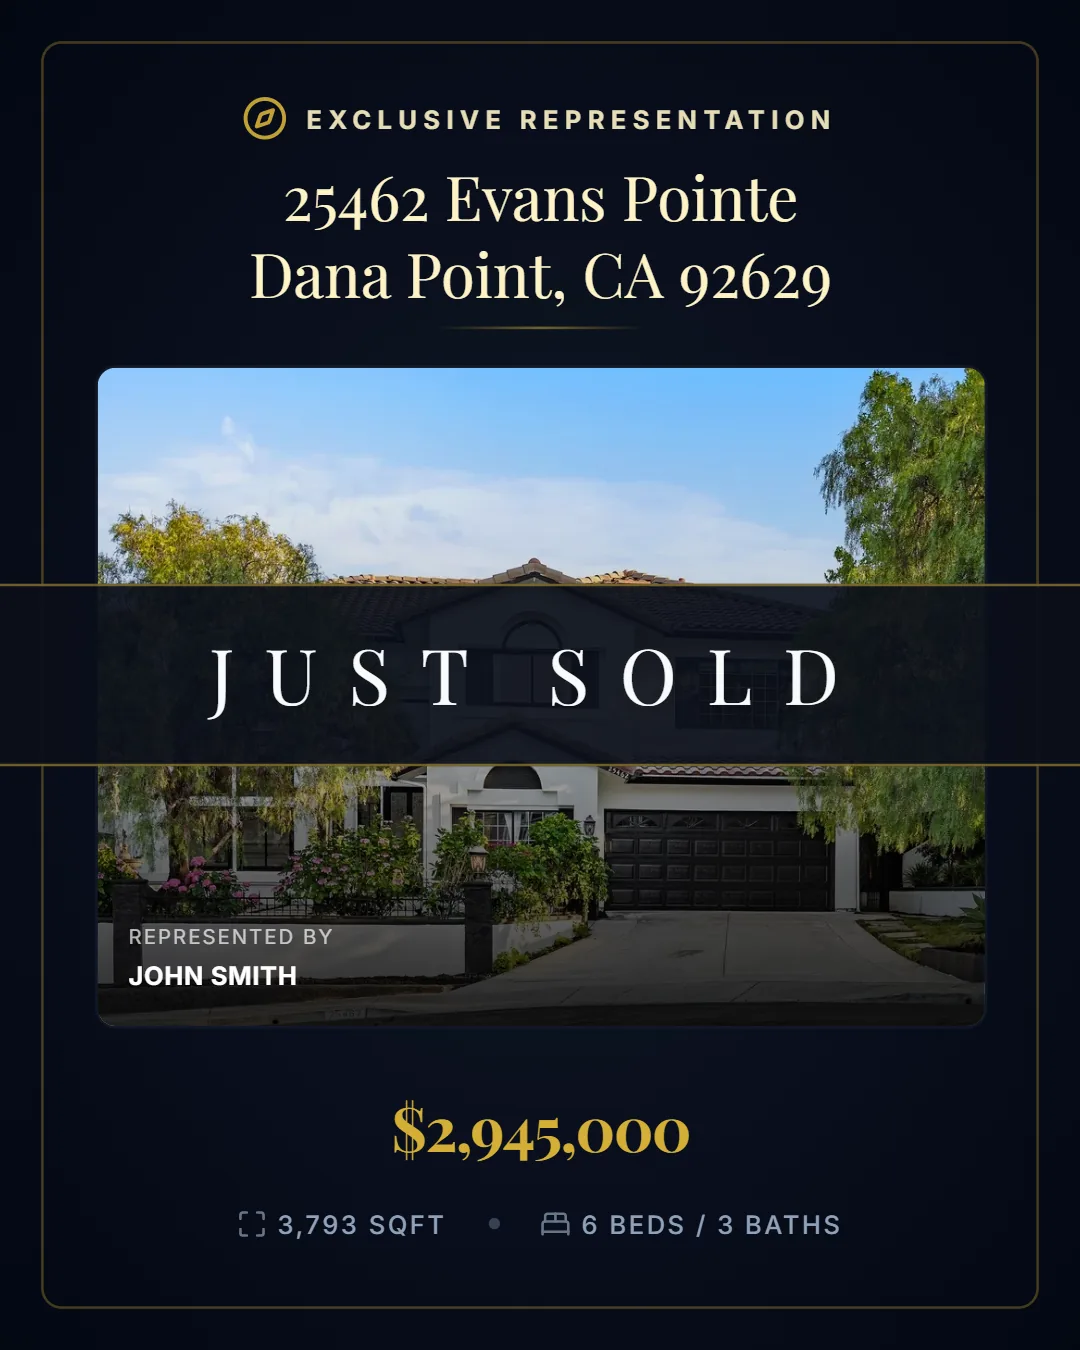
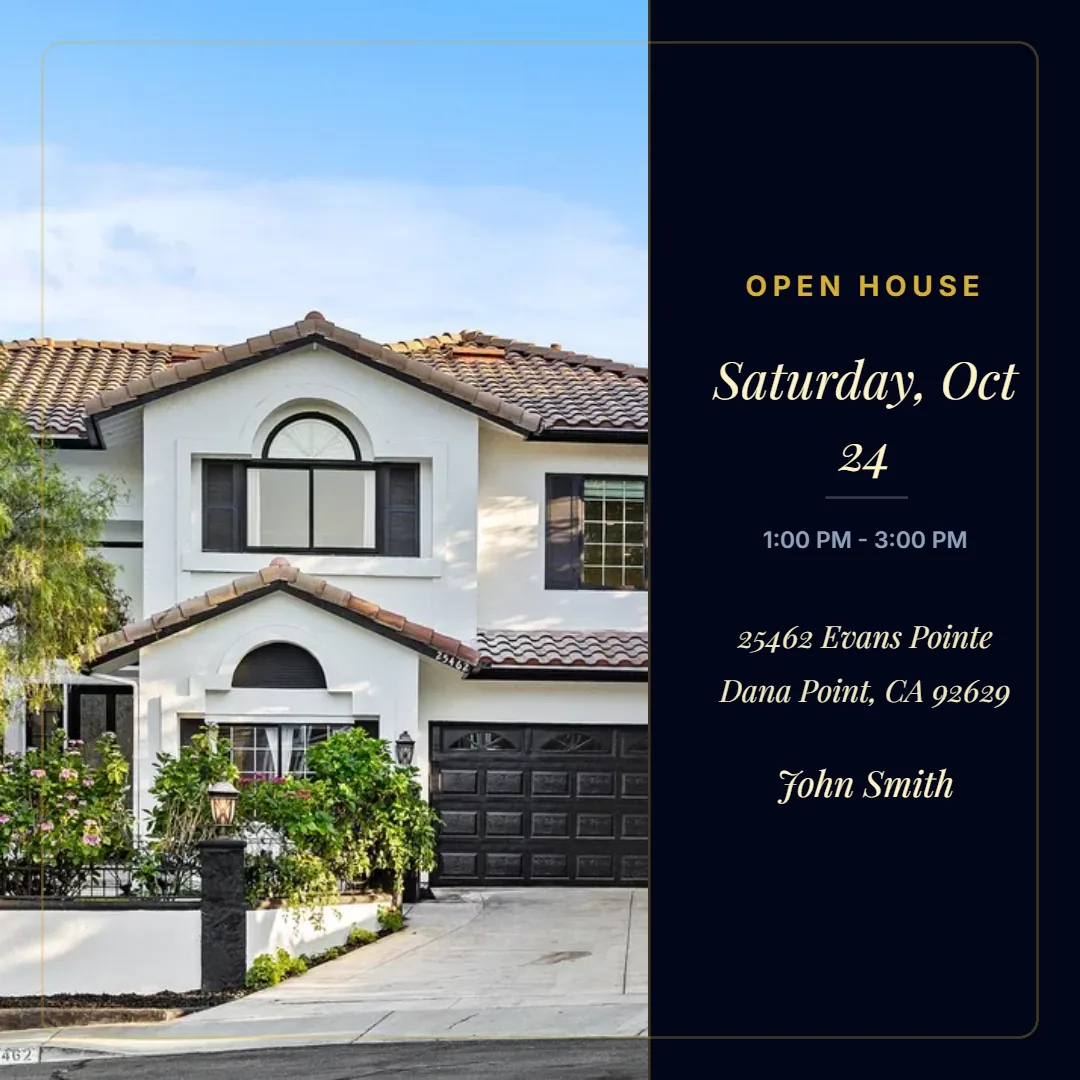
Opens on 25462 Evans Pointe, the listing in our sample posters. The price and the size are that listing's. Everything else is an ordinary assumption, so type over any figure.
The note rate from the lender, not the APR.
From the tax record for this address.
A share of the loan. Charged only while the down payment is under 20%.
Monthly payment
$18,092
Where it goes
- Principal and interest
- $14,892
- Property tax
- $2,700
- Home insurance
- $500
- Association dues
- $0
- Mortgage insurance
- $0
The loan
- Loan amount
- $2,356,000
- Down payment (20%)
- $589,000
- Total interest
- $3,004,948
- Total of monthly payments
- $6,512,948
No mortgage insurance, because the down payment is 20% or more.
The working
- Loan amount$2,945,000 − $589,000 down$2,356,000
- Principal and interest$2,356,000 at 6.5% over 360 payments$14,891.52
- Property tax$32,400 ÷ 12$2,700
- Home insurance$6,000 ÷ 12$500
- Monthly paymentThe lines above, added$18,092
- Total interest$14,891.52 × 360 − $2,356,000$3,004,948
Estimates only. Not financial, legal or tax advice.
Worth knowing
- Use the note rate
- Enter the rate on the lender's quote, not the APR. The APR folds fees into the rate and overstates the payment.
- The tax bill can change at the sale
- Many counties reassess at the sale price, so the current owner's bill can sit well below what the buyer will pay.
- Mortgage insurance ends
- On a conventional loan it comes off once the balance reaches 80% of the price. Until then it is part of the payment.
- What is left out
- Utilities, upkeep and special assessments. Lender fees belong to the closing costs, not the monthly payment.
Turn this listing into a poster.
Enter the listing once and the studio lays out the flyers, social posts and open house graphics. An address typed into a tool here comes with you.
Open the studio